Your Child’s Future: The Benefits of IULs and Cash-Value Life Insurance (2026 Guide)
Building permanent wealth, tax-free financial liquidity, and lifelong peace of mind starts long before your child steps into the world on their own. Learn how Indexed Universal Life (IUL) policies work in 2026.
Calculate Your Child’s Quote Book a Family Financial ReviewSkip to Section
Overview What is an IUL? Why 0% Floor Matters Power of Compounding Video Guide When to Buy When NOT to Buy Key Benefits Risks & Charges Average Costs 529 vs IUL Comparison Online Quoter Tool 4-Step Setup FAQBuilding a Financial Head Start in 2026
As parents and grandparents, we dream of providing our children with every advantage: debt-free higher education, early financial literacy, seed money for a first business, or a down payment on a place to call home. While traditional 529 savings plans and index mutual funds remain popular choices, forward-thinking families are turning to a dual-purpose tool: Indexed Universal Life (IUL) Insurance.
An IUL is not simply insurance against life’s worst-case scenarios; when structured correctly for a minor, it functions as a highly flexible, tax-advantaged private wealth vault. It builds cash value year after year, completely insulated from market crashes, giving your child financial options they can tap at any age—all while locking in dirt-cheap insurability for their entire lifetime.
What is Indexed Universal Life (IUL) Insurance?
An Indexed Universal Life policy is a specialized form of permanent cash-value life insurance. Unlike temporary “term insurance,” an IUL stays in place for your child’s entire life. Every premium payment you make is divided into two parts: one portion pays for the bare-minimum cost of life insurance coverage, while the remainder flows directly into a tax-advantaged cash value growth account.
1. Lifelong Protection
Secures a guaranteed, income-tax-free death benefit. Purchasing coverage during childhood locks in baseline health ratings before any adult medical conditions ever arise.
2. Market Index Tracking
Your money is not directly invested in stock markets. Instead, your cash growth is credited interest linked to top-performing market indices like the S&P 500® or NASDAQ-100.
3. Downside Capital Protection
Includes a contractual 0% Interest Floor. If Wall Street plummets 20% or 30% in a market panic, your child’s account balance simply stays flat at 0% loss.
4. Tax-Free Policy Liquidity
Through structured policy loans and withdrawals, your child can pull cash out tax-free at age 18, 25, 40, or 65 to fund major life milestones without triggering IRS tax events.

The Scenario: John and Mary welcome their baby boy, James, in 2026. Wanting to set him up for success, they establish a child IUL with a $100,000 baseline death benefit and contribute $150 per month ($5/day).
The Mechanics: The cash value tracks index growth over 18 years. Because James is so young, insurance charges inside the policy are minimal—allowing roughly 85% to 90% of every dollar contributed to build up inside the compounding cash account.
The Outcome: When James turns 18, his cash value balance is substantial. He takes a tax-free policy loan to cover his college expenses and buy a reliable car. Because he used a policy loan, his underlying account value continues earning interest, giving him momentum as he steps into adulthood!
Why the 0% Floor Matters in Modern Markets
If you invest $100,000 directly in the stock market and suffer a 30% drop during a recession, your balance plunges to $70,000. To simply get back to even, your remaining funds must earn a 42.8% gain just to recover what you lost!
This cycle of recovery is known as “negative compounding.” It destroys long-term portfolio growth. The 0% floor on an IUL permanently eliminates this risk:
| Market Year / Index Performance | Direct Stock Market Account | Child IUL Cash Value Account (Cap: 9.5%, Floor: 0%) |
|---|---|---|
| Year 1: S&P 500 Rises +15.0% | Gains +15.0% (Full upside) | Gains +9.5% (Capped at maximum growth ceiling) |
| Year 2: Recession Hits (-22.0%) | Loses -22.0% of total accumulated balance | Gains 0.0% (Account balance remains completely protected) |
| Year 3: Market Recovers +12.0% | Gains +12.0% (Still trying to recover baseline) | Gains +9.5% (Grows directly on top of protected principal) |
The Power of Compounding Interest Over Time
Time is the ultimate compounder of wealth. When an IUL is opened for a child at age 0 or 1, compounding interest operates across an unprecedented 20, 40, or 60-year timeline.
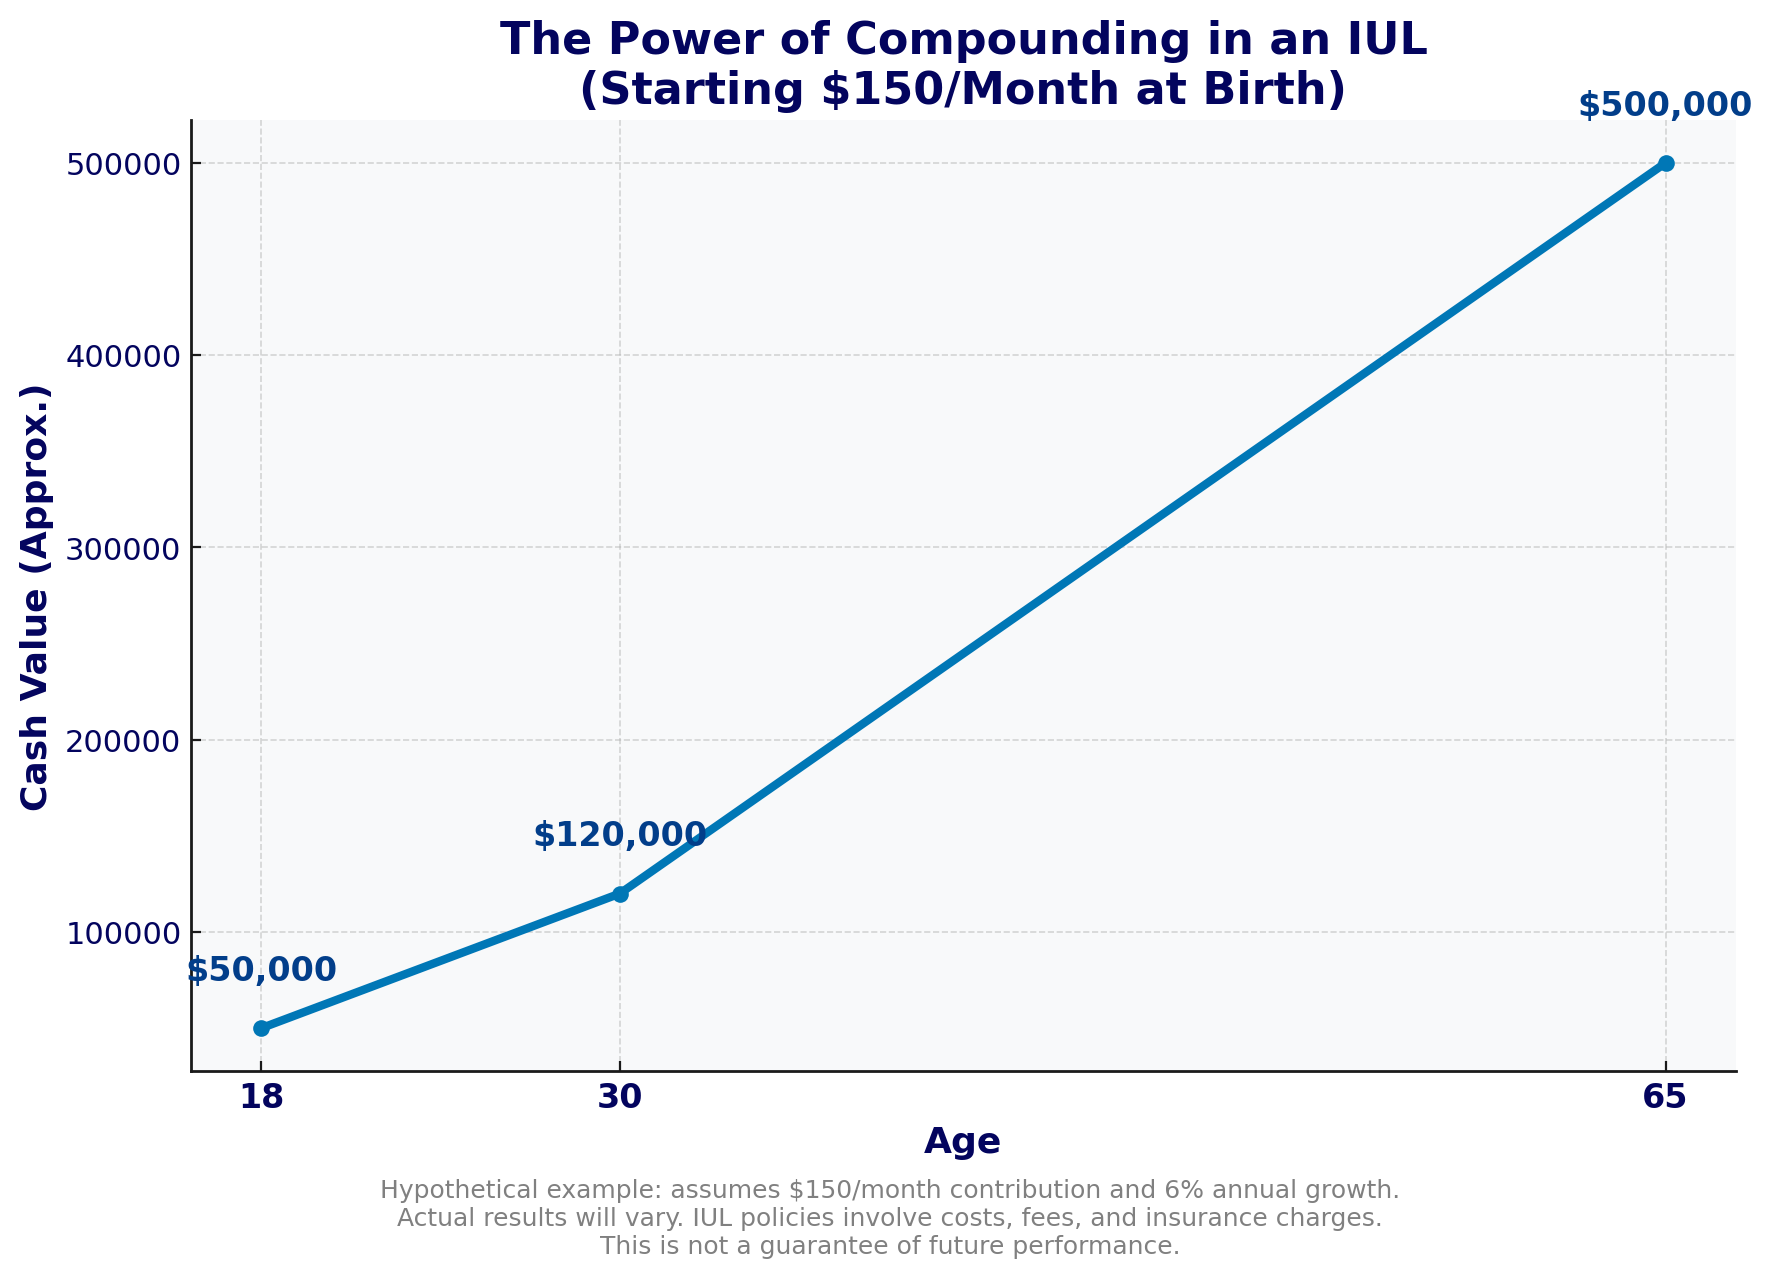
Imagine allocating $150/month into your child’s IUL from birth until age 18 (a total family contribution of $32,400):
- At Age 18 (College & Early Adult): Cash value available to pull out for tuition, trade school, or launching a business venture.
- At Age 30 (First Home & Family): Even if you stop adding money at age 18, the policy continues compounding internally, creating a major nest egg for a home down payment.
- At Age 65 (Tax-Free Retirement): The policy cash value can reach hundreds of thousands of dollars, ready to be tapped for tax-free retirement income!
Deep Dive: Watch How Child IULs Work
In this video breakdown, Policy Engineer walks through the mechanics of cash-value policies, how index crediting works, and why starting early changes the math entirely:
When to Purchase an IUL Policy
The optimal time to buy an IUL for your child is **as early as possible**—ideally within their first year of life, or as soon as your budget allows.
1. Lowest Possible Premiums
Life insurance pricing is calculated directly on age and mortality risk. A newborn or toddler has the absolute lowest insurance cost metrics possible, meaning more of your premium goes toward building cash.
2. Locking In Health Insurability
None of us can predict the future. Childhood asthma, juvenile diabetes, or physical injuries can complicate getting life insurance later. Purchasing early locks in guaranteed coverage for life.
3. Maximum Compounding Runway
A policy started at age 0 has 18 full years of compounding growth before your child ever steps foot on a college campus, and 65 years before retirement!
When NOT to Purchase an IUL
At Policy Engineer, we believe in complete transparency. An IUL is a fantastic financial vehicle, but it is **not** right for every single family budget or situation. You should pass on an IUL if:
- You Cannot Commit to Long-Term Premiums: IUL policies carry front-loaded administrative costs. If you surrender or drop the policy after only 2 or 3 years, you will lose money.
- You Need Cash Next Year: Cash value takes 5 to 7 years to build past initial policy charges. If you need liquidity for short-term savings (like a vacation next summer), stick to a standard high-yield savings account.
- You Only Want Death Protection: If your sole concern is covering pure mortality risk without any wealth building, pure term insurance is cheaper.
7 Key Benefits of Child IUL Policies
1. Tax-Free Retirement Income
Under IRS Code Section 7702, cash value growth inside a life insurance policy accumulates tax-deferred, and properly structured policy loans allow withdrawals 100% tax-free.
2. Unrestricted Money Usage
Unlike 529 plans (which penalize you 10% if funds aren’t used for approved education), IUL cash can be used for anything: a wedding, business startup, real estate down payment, or world travel.
3. FAFSA Aid Protection
Money stored in cash-value life insurance is legally exempt from FAFSA calculations for college financial aid. It won’t hurt your child’s chances of receiving federal grant money!
4. Positive Policy Arbitrage
When taking a policy loan, your full cash value balance stays inside the indexing account earning interest, even while you use the borrowed money in the real world.
5. Built-In Living Benefits
Many modern 2026 IULs include living benefit riders that allow access to the death benefit early if the child suffers a severe critical, chronic, or terminal illness.
6. Flexible Premium Payments
If times get tough financially, you can lower your monthly payments or let accumulated cash value pay internal policy charges for a period of time without losing coverage.
Understanding Risks, Fees, and Internal Costs
To ensure an IUL policy performs as expected, parents must understand the internal costs that govern how these policies operate:
| Internal Policy Fee | What It Pays For | How Policy Engineer Optimizes It |
|---|---|---|
| Cost of Insurance (COI) | The pure cost of providing the death benefit coverage. Scales up as the insured ages. | We structure child policies with the minimum allowable death benefit relative to premium to keep COI costs extremely small. |
| Cap Rates & Participation Rates | Limits maximum growth in high market years (e.g., a 9% cap means if the index rises 18%, you receive 9%). | We partner only with top-tier, financially strong carriers (A+ rated) with strong histories of maintaining high cap rates. |
| Premium Expense Charges | Deducted upfront from each payment to cover state premium taxes and carrier administration (typically 4% to 8%). | Factored directly into policy projections so there are zero surprises down the road. |
How Much Does a Child IUL Cost?
There is no single mandatory price tag for an IUL. Because you control the funding level, premiums can range from **$50/month up to $500+/month** depending on your budget and goals.
- Starter Tier ($50 – $100/month): Secures basic lifelong protection ($50k–$100k death benefit) and builds a modest, steady cash fund for high school graduation or trade school.
- Growth Tier ($150 – $250/month): The standard sweet spot. Generates high compounding speed to fund college tuition, launch a business, or secure a primary residence down payment in their late 20s.
- Legacy Wealth Tier ($300+/month): Max-funds the policy to create a tax-free generational wealth foundation that provides substantial tax-free income through adulthood and retirement.
Head-to-Head: 529 College Savings Plan vs. Child IUL
Many parents wonder whether to open a state 529 plan or a cash-value IUL policy. Here is how they compare side-by-side in 2026:
| Feature / Parameter | Traditional 529 College Plan | Child IUL Policy |
|---|---|---|
| Primary Purpose | Higher Education Funding Only | Wealth Building + Life Insurance Protection |
| Market Risk | Full Market Exposure (Can lose principal in market downturns) | 0% Downside Floor (Principal & gains protected) |
| Use of Funds | Penalized 10% + tax if used for non-education expenses | 100% Flexible (College, home, business, retirement, etc.) |
| FAFSA Financial Aid Impact | Counted as parental asset (Reduces college aid eligibility) | Exempt (Does not count against financial aid formulas) |
| Tax Treatment | Tax-free withdrawals for qualified education only | Tax-free growth & tax-free access via loans at any age |
| Lifelong Protection | None (Account ends once funds are spent) | Provides lifelong protection & wealth growth into adulthood |
Calculate Your Child’s Quote Online
Curious what an IUL or cash-value life insurance plan looks like for your child or grandchild? Use our interactive self-service quoter below to run live pricing and explore custom coverage options instantly!
Need custom funding assistance? Schedule a quick consultation with our team.
How to Set Up a Child IUL in 4 Simple Steps
Decide on an amount you can comfortably contribute each month without straining your household finances ($100, $150, $200+).
Work with a licensed Policy Engineer specialist to structure the policy for maximum cash accumulation by setting the death benefit to the lowest legal limit possible.
Complete a quick 10-minute online application. No physical medical exams are required for children—just basic health history questions.
Set up automatic monthly bank transfers to fund the policy on autopilot, letting time and compound interest do the rest!
Frequently Asked Questions (FAQ)
Who owns the IUL policy while my child is young?
You (the parent or grandparent) are the legal policy owner and retain 100% control over the account, cash withdrawals, and beneficiary designations. Once your child reaches an age you deem appropriate (e.g., 21 or 25), you can easily transfer legal ownership over to them.
What happens if I need to stop paying premiums temporarily?
One of the best features of an IUL is premium flexibility. If you run into temporary financial hardship, you can lower your monthly contribution or pause it completely. As long as there is enough accumulated cash value inside the policy to cover the basic internal monthly fees, your child’s coverage stays active!
Can grandparents open an IUL for a grandchild?
Yes! Grandparents can easily apply for and fund an IUL for a grandchild. You simply need the parent or legal guardian’s signature on the application form.
Is the cash value guaranteed to grow?
Growth is linked to index performance. In years when the market index is positive, your cash value earns credited interest up to the policy cap. In years when the market loses money, your cash value is protected by the 0% floor, ensuring you never lose principal or accrued interest due to market downturns.
How does my child take money out of the policy when they grow up?
They can access cash at any time through tax-free withdrawals (up to their cost basis) or tax-free policy loans. Policy loans use the cash value as collateral, keeping the underlying cash balance working and compounding inside the policy.
Ready to Build Your Child’s Wealth Engine?
Our team of Policy Engineer specialists is here to help you structure the perfect plan for your family’s goals.
Run Instant Child Quote Schedule a 1-on-1 Strategy Call© 2026 Policy Engineer. All rights reserved. Policy features and rates subject to state availability and carrier underwriting guidelines.
Setting up an IUL or cash-value life insurance plan for your child is straightforward. Here are the steps to get started:
-
-
-
Research: Begin by researching reputable insurance companies that offer child-specific policies. Look for strong financial ratings and customer reviews to ensure reliability.
-
Consult an Insurance Agent: Reach out to a licensed insurance agent who specializes in life insurance and can guide you through the available options based on your child’s needs and your financial goals.
-
Choose the Right Plan: Select an IUL or cash-value life insurance plan that aligns with your long-term objectives, considering factors like premium affordability and potential investment growth.
-
Set Up the Policy: Once you’ve chosen the policy, work with your insurance agent to complete the necessary paperwork and set up the plan. Make sure to review the policy details and ask any questions before finalizing the agreement.
-
Monitor and Review: Keep a regular check on the policy’s performance and periodically review it with your insurance agent to ensure it continues to meet your child’s evolving needs.
-
-
How to Set Up an IUL for your (grand)child
Other Types of Cash-Value Life Insurance and 529 plans:
There are several different types of cash-value life insurance, including IULs, variable universal life insurance (VUL), and whole life insurance. Each type of policy has its own advantages and disadvantages.
-
VUL insurance combines life insurance coverage with investment options similar to mutual funds. Policyholders can allocate premiums into various investment accounts, giving them the potential for higher returns but also exposing them to market risks.
In comparison with Index Universal Life Insurance,
- VULs also offer the potential for growth,
- The policyholder has more control over how the funds are invested.
- However, VULs can be more complex than IULs, and there is a greater potential for losses.
-
Whole life insurance is another type of cash-value life insurance that offers guaranteed death benefits, fixed premiums, and cash value accumulation. The cash value grows at a predetermined rate and can be accessed through loans or withdrawals. Since, the cash value of a whole life policy grows at a predetermined rate, there is less potential for growth than with an IUL or VUL.
-
UL insurance provides flexibility in premium payments and the potential for cash value growth. Policyholders can adjust premium amounts and have the option to invest the cash value in various accounts, including fixed interest accounts or market-based accounts. The cash value of a universal life policy grows at a predetermined rate, which is typically lower than the rate of return on the stock market. However, universal life insurance is less risky than IULs, as the cash value is not subject to market fluctuations.
-
A 529 plan is a tax-advantaged savings plan designed to encourage saving for future education costs. Here are some key points about 529 plans:
Pros:
- Tax Advantages: Contributions grow tax-deferred, and withdrawals for qualified education expenses are tax-free.
- High Contribution Limits: Most 529 plans have high contribution limits, allowing substantial savings.
- State Tax Benefits: Many states offer tax deductions or credits for contributions to a 529 plan.
- Control: The account owner retains control over the account and can change beneficiaries.
Cons:
- Limited Use: Funds must be used for qualified education expenses, or you’ll face penalties and taxes on earnings.
- Market Risk: The investments in a 529 plan are subject to market risk, which can affect the value of your savings.
- Impact on Financial Aid: Assets in a 529 plan can impact a student’s eligibility for financial aid.
Choosing between a 529 plan and an IUL depends on your specific goals and circumstances. If your primary focus is on saving for education with tax advantages, a 529 plan might be the better option. However, if you want more flexibility in how you use the funds, along with the added benefit of life insurance protection, an IUL could be a more suitable choice.
To discover more about the differences between 529 plans and IUL, check out our blog on this topic! https://policyengineer.com/differences-between-529-plans-and-indexed-universal-life-insurance-iul/How IULs Compare to Other Options
Parents often ask, “Why not just use a 529 plan?” or “Shouldn’t I just buy term life?” Here’s a quick breakdown:
FeatureIUL for Kids529 PlanTerm LifeUse of FundsFlexible—education, housing, retirement, businessEducation only (penalties for other uses)No cash value, only death benefitCash Value GrowthIndexed growth + 0% floorMarket-linked, no floorNoneTax BenefitsTax-advantaged distributionsTax-free if for educationN/AProtectionLifelong insurance coverageNoneOnly while the term lastsAn IUL isn’t just insurance—it’s a strategy. It’s about giving your child options, freedom, and a financial head start that keeps compounding for decades.
A small decision today can unlock lifelong opportunities for your child tomorrow.
Flexibility & Living Benefits
One of the strongest features of IULs is premium flexibility. Parents can start small, increase payments later, or pause during tough financial seasons.
Plus, many IULs include living benefits:
-
Early access to death benefits in case of critical illness or long-term care needs.
-
Provides not just a savings tool, but also a safety net during life’s unexpected turns.
Timing Is Everything: Start Early
Starting an IUL for your child while they’re young locks in:
-
Lower premiums (because of age and health).
-
More years of compounding growth.
-
A financial foundation before adulthood.
The earlier you start, the more powerful the results.