Differences Between 529 Plans and Indexed Universal Life (IUL) Insurance
Which savings vehicle gives your child or grandchild the strongest financial head start? Compare tax treatment, market risk, FAFSA impact, and flexibility in 2026.
Book a Family Financial ReviewSkip to Section
Overview What is a 529 Plan? What is an IUL? Comparison Table FAFSA Aid Rules Market Risk & 0% Floor Use Flexibility Video Guide Online Quoter Tool Which Should You Choose? FAQChoosing the Right Wealth Engine for the Next Generation
When planning for a child’s future, parents and grandparents want a strategy that protects capital, maximizes tax savings, and opens doors down the road. For decades, the traditional 529 College Savings Plan was the default choice. However, modern parents in 2026 are increasingly comparing 529 plans against **Indexed Universal Life (IUL) Insurance**.
While both vehicles offer valuable tax-advantaged growth, they operate on completely different rules when it comes to market exposure, financial aid calculations, and what happens if your child decides not to attend a traditional four-year college.
What is a 529 College Savings Plan?
A 529 plan is a state-sponsored investment account designed specifically for higher education expenses. Contributions are invested directly into mutual funds, stock index funds, or age-based portfolios.
1. Tax-Free Qualified Growth
Earnings grow tax-deferred and can be withdrawn completely tax-free—provided the money goes directly toward qualified higher education costs.
2. Full Market Exposure
Because funds are invested in real market securities, your balance rises and falls with market volatility. A sudden economic crash right before college can impact your child’s savings balance.
3. Specific Usage Restrictions
If funds are withdrawn for non-educational expenses (like starting a business or buying a first home), the earnings portion is subject to ordinary income tax plus a **10% IRS penalty**.
What is Indexed Universal Life (IUL) Insurance?
An Indexed Universal Life policy is a permanent cash-value life insurance plan that combines lifelong coverage with a tax-deferred wealth accumulation engine.
1. Protected Index Crediting
Cash growth tracks major equity market indices (like the S&P 500®), but your funds are never directly invested in stocks. You gain interest when the index rises, but suffer 0% loss when it drops.
2. 100% Flexible Cash Access
Under IRS Code Section 7702, accumulated cash value can be accessed tax-free via policy loans for any purpose—college tuition, trade school, a home down payment, or a business launch.
3. Lifelong Insurability
Opening an IUL during childhood locks in the lowest possible life insurance cost structure and guarantees coverage for life, regardless of future health conditions.

Side-by-Side Comparison: 529 Plan vs. Child IUL
Here is how 529 plans and cash-value IUL policies compare across key financial categories in 2026:
| Feature / Criteria | Traditional 529 Plan | Indexed Universal Life (IUL) |
|---|---|---|
| Primary Objective | Higher Education Savings | Multi-Purpose Wealth + Life Protection |
| Market Risk | Full Market Exposure (Can lose principal) | 0% Downside Floor (Gains & principal protected) |
| FAFSA Aid Impact | Counted as parental asset (Reduces college aid) | Exempt (Does not impact FAFSA math) |
| Use of Funds | Qualified Higher Education Only | Unrestricted (Anything at any age) |
| Non-Qualified Penalty | 10% Penalty + Income Tax on earnings | None (Tax-free policy loans) |
| Lifelong Value | Ends once funds are spent | Continues into adulthood & retirement |
How Each Account Impacts College Financial Aid (FAFSA)
When applying for federal college financial aid, the Student Aid Index (SAI) formula scrutinizes family assets. How your savings are structured makes a big difference:
529 plans owned by parents are reported as parental assets on the FAFSA, with up to 5.64% of the account value counted toward expected family contributions. While this percentage is relatively small, a large 529 balance can directly lower the amount of grant money your student receives.
Under federal guidelines, the cash value held inside life insurance policies is **completely exempt from FAFSA asset calculations**. You can hold substantial accumulated cash value inside an IUL without impacting your child’s eligibility for needs-based college grants or federal student loans.
Market Exposure vs. The Contractual 0% Floor
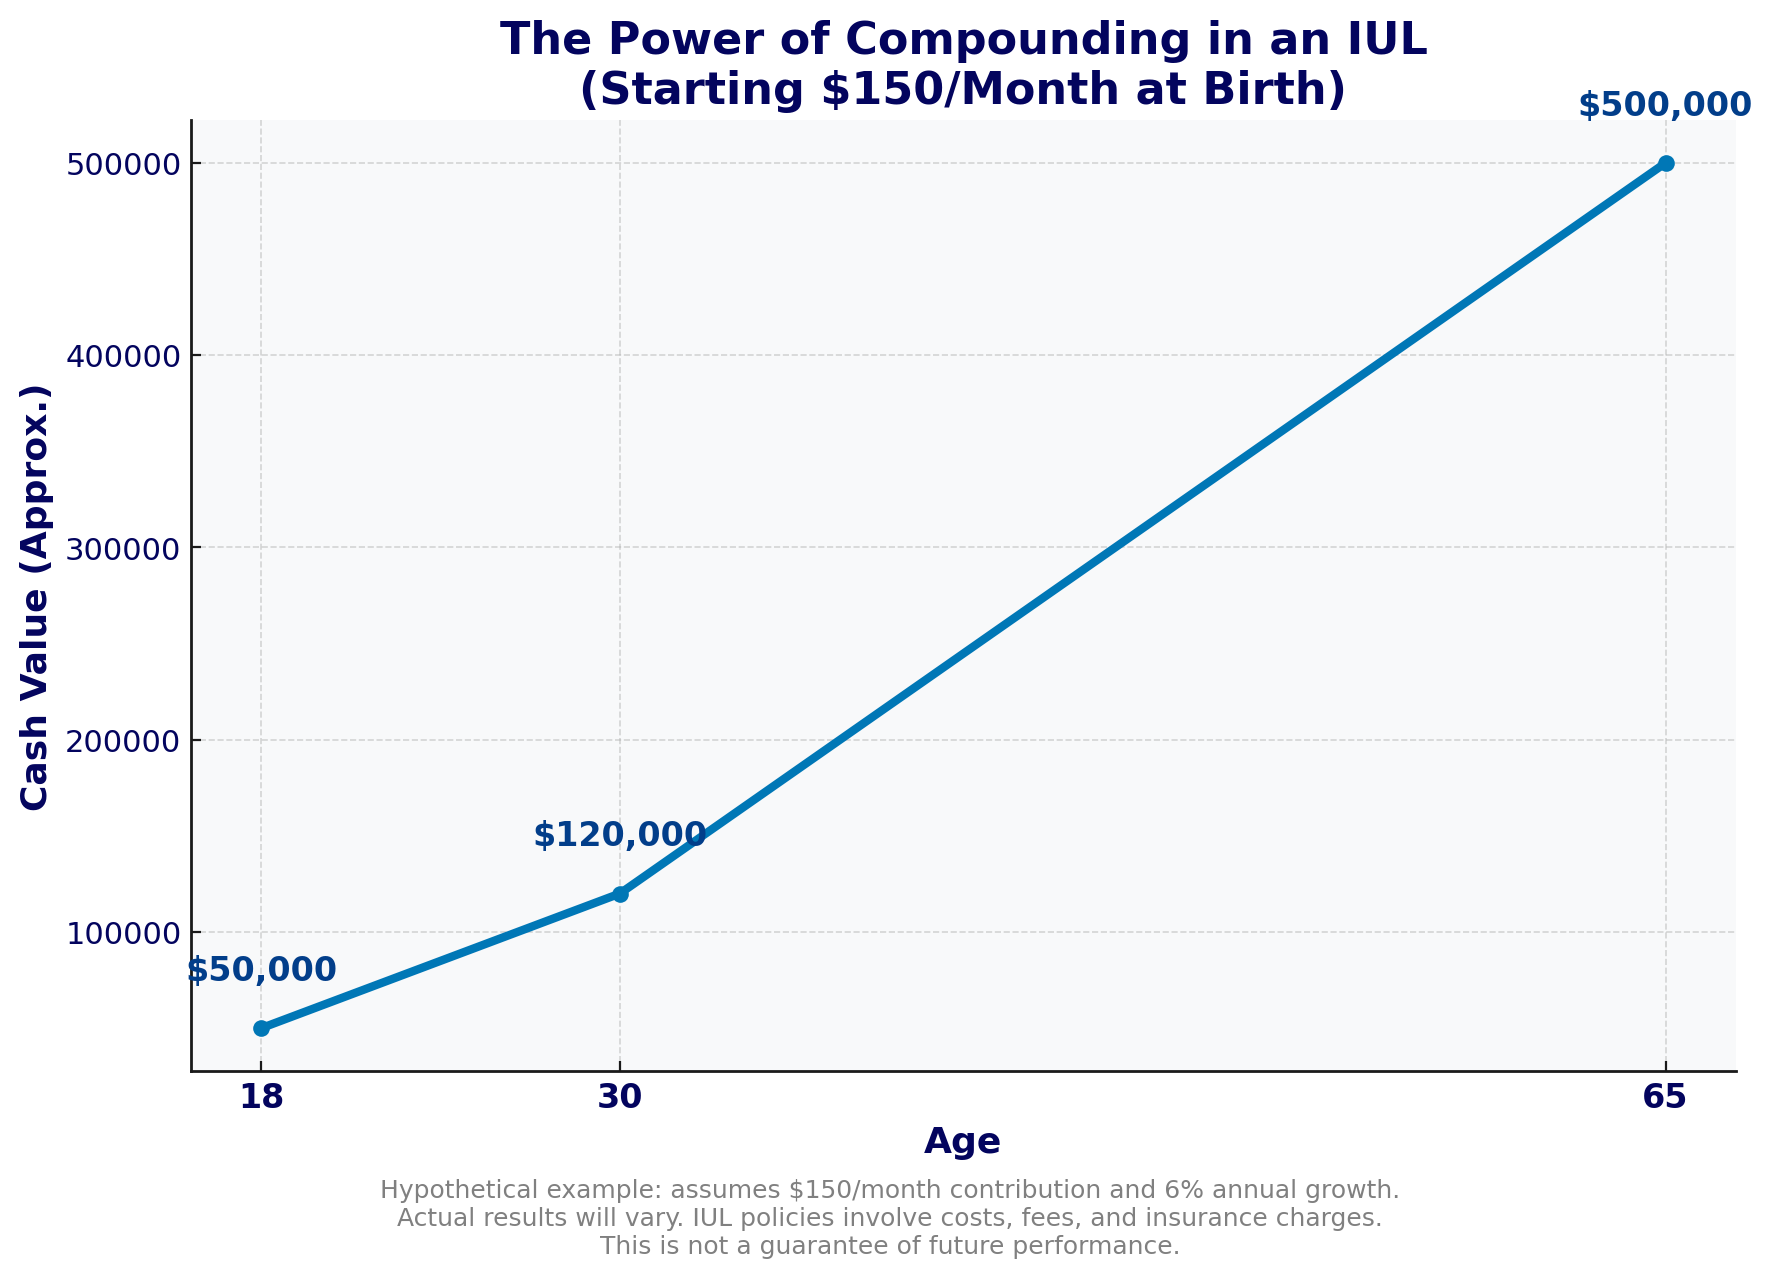
Timing matters when investing for a specific milestone like college. If the stock market experiences a severe pullback right as your child turns 18, a traditional 529 plan forces you to absorb that loss or delay tuition payments.
Flexibility: What If Your Child Doesn’t Go to College?
Higher education path choices are changing rapidly. Trade certifications, entrepreneurship, real estate investment, and creative careers are increasingly common alternatives to traditional four-year degrees.
- With a 529 Plan: If your child chooses not to attend college, you must either transfer the account to a relative, convert a limited amount into a Roth IRA (subject to strict IRS eligibility limits), or pay a 10% penalty plus ordinary income taxes to withdraw the cash.
- With an IUL Policy: The money belongs to the policy owner with zero restrictions. Your child can use accumulated cash value to start a business, purchase their first home, fund a wedding, or keep the money compounding tax-free for retirement.
Deep Dive: Watch How Child IULs Work
Watch Policy Engineer break down cash-value insurance, index crediting mechanics, and how compounding changes over a multi-decade timeline:
Calculate Your Child’s Quote Online
Explore custom life insurance pricing and cash growth options for your child or grandchild using our interactive tool below:
Want help setting your targets? Schedule a quick consultation with our team.
The Verdict: Which Should You Choose?
Choose a 529 Plan If:
- You are 100% certain the funds will be used strictly for higher education costs.
- You want state tax deduction benefits offered by your home state’s 529 plan.
- You prefer direct stock market fund investments and accept market volatility risk.
Choose an IUL Policy If:
- You want 100% flexibility for college, home down payments, or business ventures.
- You want to protect capital against market downturns with a guaranteed 0% floor.
- You want cash value hidden from FAFSA financial aid formulas.
- You want to lock in lifelong, permanent health insurability for your child.
Frequently Asked Questions (FAQ)
Can I have both a 529 plan and an IUL policy?
Yes! Many families utilize a hybrid approach—funding a 529 plan up to anticipated tuition costs while funding an IUL to build flexible tax-free wealth and lock in permanent health insurability.
Can grandparents fund an IUL for a grandchild?
Absolutely. Grandparents can set up and fund an IUL policy for a grandchild with the parent or legal guardian’s signature on the digital application.
Are policy loans from an IUL really tax-free?
Yes. Under IRS Section 7702, policy loans allow you to access accumulated cash value tax-free, provided the policy remains active and is properly structured.
Ready to Plan Your Child’s Financial Future?
Our team of Policy Engineer specialists is ready to help you compare scenarios and build a tailored plan for your family.
Run Instant Child Quote Schedule a 1-on-1 Strategy Call© 2026 Policy Engineer. All rights reserved. Policy features and rates subject to state availability and carrier underwriting guidelines.